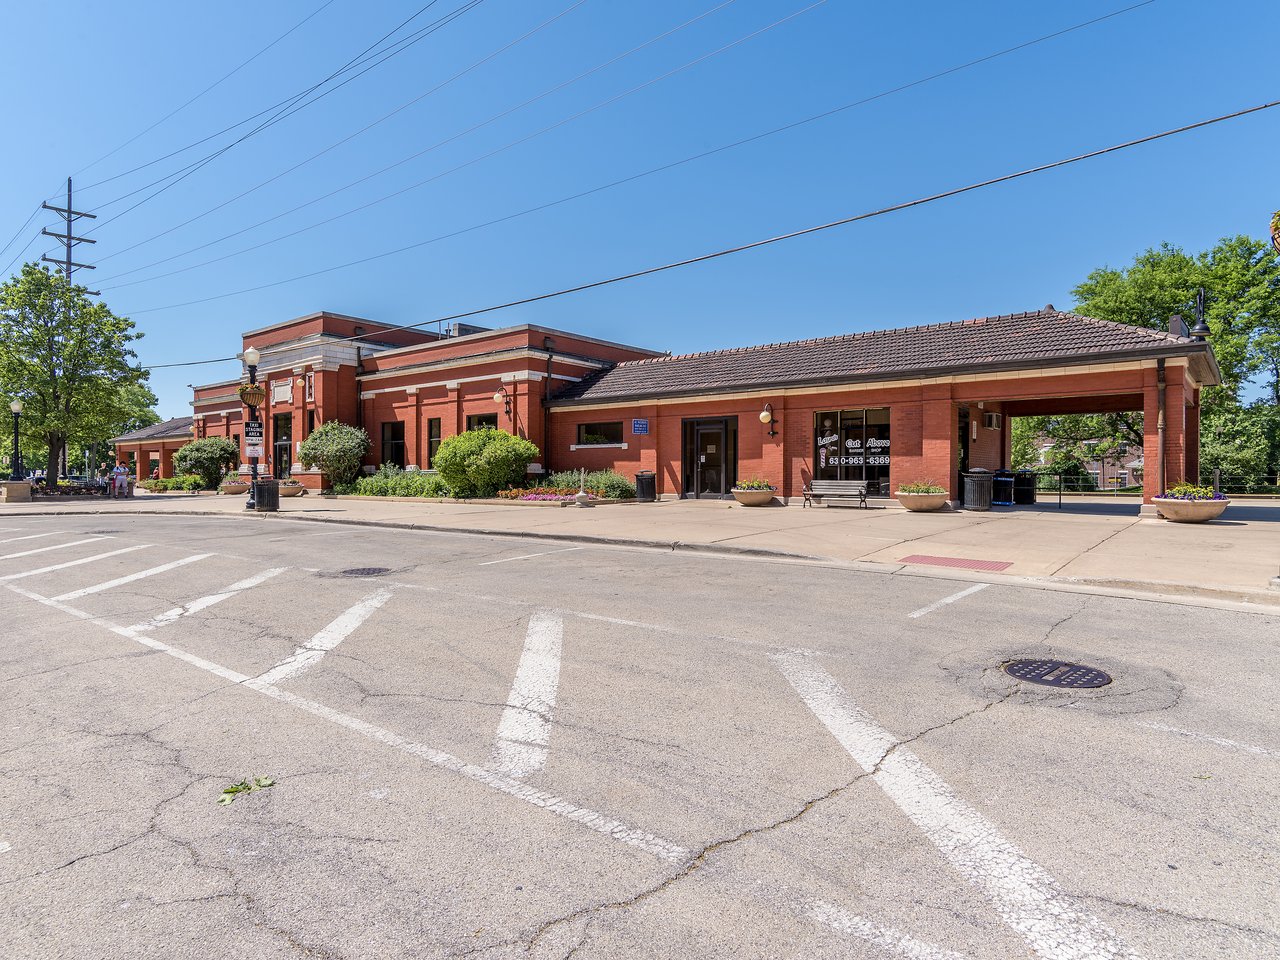
How to Start the Home Buying Process in Downers Grove
September 17, 2026
September 17, 2026
If you've been asking yourself, how do I start the home buying process in Downers Grove?, you're not alone.
Most people hit a wall right at that question, unsure whether to call a bank, scroll listings, or find a real
estate agent first. That uncertainty can stall a motivated buyer for months, sometimes longer.
The good news is that buying a home in Downers Grove is more manageable than it feels in that first
overwhelmed moment. What separates buyers who move confidently through the process from those
who spin their wheels is simply knowing the right order of steps. Skipping ahead to weekend tours before
you understand your financial picture leads to wasted time and real disappointment when a home you
love is already under contract.
This guide follows the same roadmap The Wardlow Group walks first-time buyers through during initial
consultations. It's built around the Downers Grove market specifically, not generic national advice that
ignores Illinois closing costs, DuPage County property taxes, or local assistance programs most buyers
don't know exist. Start here, work through each step in sequence, and you'll have a clear plan before
you've committed to anything.
How do I start the home buying process in Downers Grove:
check your finances first
This is the real first step, and it's the one most buyers skip. Before pre-approval, before scheduling
showings, you need to understand exactly what a lender will see when they pull your file. Walking into that
conversation without knowing your numbers puts you at a disadvantage.
What credit score do you actually need?
Most conventional loans require a minimum score of 620 to 640. FHA loans can go lower, with 580
qualifying for the standard 3.5% down payment option, or 500 if you bring 10% down. If you plan to use
any of Illinois's IHDA first-time buyer assistance programs, the minimum jumps to 640 across the board.
Pull your free credit report through AnnualCreditReport.com and review it carefully for errors before any
lender does. Disputing an error after you've already applied costs you time in a fast-moving market like
Downers Grove.
How much savings do you need ready?
Think of your savings in three separate buckets. First is your down payment, which ranges from 3% to 20%
depending on loan type. Second is closing costs, which run 2% to 3% of the purchase price in Illinois, on a
home near the Downers Grove median of approximately $549,000, that's roughly $10,000 to $16,000 in
closing costs alone. Third is cash reserves: the money lenders want to see remaining in your accounts
after you close, as a signal that you're not financially stretched the moment you get the keys.
Why your debt-to-income ratio shapes your budget
Your income matters, but lenders care equally about what you owe. Debt-to-income ratio, commonly
called DTI, compares your total monthly debt payments, including your new mortgage, to your gross
monthly income. Most conventional lenders target a DTI below 43% to 45%, with 36% or lower giving you
the strongest approval profile. This single number often determines how much home you actually qualify
for, not just what your salary suggests on paper.
Get mortgage pre-approval as your first official move
Pre-approval and pre-qualification are not the same thing. Pre-qualification is a rough estimate based on
information you report yourself. Pre-approval means a lender has verified your actual documents and
issued a conditional commitment. In Downers Grove, where homes are going under contract in five to
twelve days, sellers simply don't take offers seriously without a pre-approval letter in hand.
Mortgage pre-approval in Downers Grove: documents and timeline
Having your documents ready before your first lender call shortens the process significantly. Gather two
years of W-2s or tax returns (especially important if you're self-employed), recent pay stubs from the last
30 days, two to three months of bank and asset statements, a government-issued ID, and a list of your
current monthly debts. If you're planning to use gift funds toward your down payment, your lender will also
need a gift letter documenting the source. Most lenders can issue a pre-approval decision within one to
three business days once they have a complete file.
Local lenders who know DuPage County timelines
Downers Grove buyers have solid options at both the local and national level. Community Bank of
Downers Grove, Compass Mortgage, and Guaranteed Rate are frequently recommended by buyers and
agents in the Downers Grove area, alongside national banks like Chase and U.S. Bank with local branch
presence. A lender who operates in DuPage County regularly understands local closing timelines and
coordinates more naturally with local title companies and attorneys, which matters when you're up
against competing offers.
What buying in Downers Grove actually costs in 2026
Downers Grove is a desirable market for real reasons: strong schools, Metra BNSF access for Chicago
commuters, and a genuinely walkable downtown near Main Street. That desirability shows up in the
numbers. Getting an honest cost picture before you set your budget prevents the frustration of falling in
love with homes you can't actually afford to close on.
Current home prices and what your budget unlocks
The median sale price in Downers Grove is approximately $549,000 based on recent 2026 data. Condos
and townhomes come in lower and offer a realistic entry point for first-time buyers. Single-family homes
in the most sought-after school zones frequently push above that median. With roughly 168 homes
currently listed across the market, inventory exists, but it moves. Homes that are priced well and show
well typically go under contract within one to two weeks.
DuPage County property taxes: the cost most buyers underestimate
Property taxes in DuPage County carry an effective rate of approximately 1.85%, though the exact figure
varies based on overlapping taxing bodies including school districts, the park district, library, and
township. On a home priced at $549,000, you should budget for an annual tax bill somewhere between
$7,200 and $8,600. This is one of the most consistently underestimated costs for first-time buyers, and it
directly affects your monthly mortgage payment calculation. Always ask your lender to include the
estimated tax escrow in the payment figure they show you.
Closing costs and cash at the table
In Illinois, buyers should plan for 2% to 3% of the purchase price in closing costs. On a $500,000 home,
that's $10,000 to $15,000 due at closing, separate from your down payment. Common line items include
title insurance, attorney fees, and recording fees. Request a Loan Estimate from your lender early in the
pre-approval process so you can see the full picture before you're emotionally invested in a specific
property.
Assistance programs that reduce what you need upfront
Many buyers in the Downers Grove area assume they need 20% down to be taken seriously. They don't.
Illinois and DuPage County have programs built specifically to lower that barrier, and each year buyers
leave thousands of dollars in available assistance unused simply because they didn't know to ask about it
early enough in the process.
IHDA programs and what they offer
The Illinois Housing Development Authority administers several assistance options worth knowing.
IHDAccess Home provides up to $15,000 toward down payment and closing costs paired with a 30-year
fixed mortgage. IHDAccess Forgivable offers up to $6,000 as a forgivable grant, meaning you don't repay
it if you meet the occupancy requirements. IHDAccess Deferred provides up to $7,500 as a 0% interest
deferred loan. For DuPage County buyers in 2026, income limits for these programs are approximately
$143,880 for the county group, with purchase price caps around $644,000 for a single-unit property. Most
programs require a 640 minimum credit score, a homebuyer education course, and an IHDA-approved
lender.
How to actually access these programs
You don't apply to IHDA directly. Instead, you work with an IHDA-approved lender who bundles the
assistance into your mortgage application. The homebuyer education course required by most programs
is worth completing early regardless of whether you end up using assistance, because it covers
inspection, appraisal, and closing concepts that will serve you throughout the process. Plan for two to
four hours of online coursework and a modest fee, typically under $100.
Getting familiar with Downers Grove neighborhoods before you
tour
Downers Grove is not one uniform market. The neighborhood you choose affects your children's school
experience, your commute, your tax bill, and your long-term resale value. Buyers who get oriented before
they start touring make faster, more confident decisions when a good home becomes available. Those
who don't often feel paralyzed comparing properties that aren't actually comparable.
Schools, transit, and lifestyle factors to evaluate
Downers Grove is served by two main public school structures: District 58 for elementary and middle
school, and District 99 for high school, which includes both Downers Grove North and Downers Grove
South. Both districts earned a "Commendable" designation from the Illinois Report Card in 2024, the
state's top performance category. For commuters, the Metra BNSF line runs through the community with
express trains reaching downtown Chicago in approximately 30 minutes. If walkability and weekend
activity matter to you, the Main Street area offers restaurants, shops, and community events within
walking distance of several residential neighborhoods.
Downers Grove homes for sale: how to narrow your search area
Before you tour a single home, shortlist two or three priority neighborhoods based on school zone,
commute distance, and price range. Use a neighborhood guide or mapping tool to confirm which District
58 school a given address feeds into, since the boundaries don't follow the village lines uniformly. Buyers
who walk into their first showing with focused geographic criteria make offers faster and feel
significantly less overwhelmed.
Why your first call should be to a local agent, not a listing site
Most people begin their home search by browsing listings late at night on national real estate sites. That's
a reasonable way to get oriented, but it creates a distorted picture of what's actually available. By the time
you find a home you love on a public portal, a local buyer who already has an agent and a pre-approval
letter in place may have an accepted offer waiting. In Downers Grove, homes are going pending in five to
twelve days on average.
What a buyer's agent actually does for you
A buyer's agent is typically compensated through the transaction, not out-of-pocket from you as the buyer,
so there's no cost barrier to getting professional representation from the start. A strong local agent gives
you early visibility into listings, helps you build a competitive offer strategy, negotiates on your behalf, and
coordinates inspections, appraisals, attorney review, and closing so you're not figuring it out alone. In a
market where multiple-offer situations are still common, that representation is the difference between
winning a home and losing it to a better-prepared buyer.
Starting a conversation with The Wardlow Group
For buyers getting started in Downers Grove, The Wardlow Group is the natural first call. Led by Patty
Wardlow, the team has held the top agent position in this community since 2012 and ranks in the top 1%
of REALTORS nationwide. Over 90% of their business comes from referrals and repeat clients, a track
record built on results, not marketing volume. They work regularly with first-time buyers and offer no-
pressure initial consultations that give you a realistic picture of where you stand and what a workable
timeline to homeownership looks like for your situation. Reach out through the website to schedule a
conversation at any stage of the process.
Your next step: start the home buying process in Downers Grove
today
When buyers ask how do I start the home buying process in Downers Grove, the answer comes down to a
clear sequence: check your credit and savings, get pre-approved with a lender who knows this market,
build a budget that accounts for local taxes and closing costs, and connect with a local agent before you
start touring homes.
You don't need to have everything figured out before you take that first step. Most buyers who work with
an experienced local team are genuinely surprised by how quickly the confusion clears once someone
walks them through it in plain language. The process feels large until it's broken into the right sequence,
and then it becomes a series of manageable decisions.
If you're ready to move forward or simply want to talk through where you stand, The Wardlow Group offers
no-pressure consultations for buyers at any stage. Ask your questions, get honest answers, and leave
with a clear starting point before you commit to anything.
Stay up to date on the latest real estate trends.
How to Start the Home Buying Process in Downers Grove

Etiam non quam lacus suspendisse faucibus interdum. Orci ac auctor augue mauris augue neque. Bibendum at varius vel pharetra. Viverra orci sagittis eu volutpat.